If your mortgage is coming up for renewal in 2026, you’ve probably already done the math. Or maybe you’ve been avoiding it.
Either way, you’re not alone. The final major group of Canadians who locked in five-year mortgages during the pandemic’s ultra-low rate period is approaching renewal now… roughly 12% of outstanding Canadian mortgages, according to the Bank of Canada.
But the national headline doesn’t tell the Alberta story. And the Alberta story doesn’t tell the Edmonton story. Here’s what the local numbers actually say.
What’s happening in the Greater Edmonton Area right now
Before we get to the survey data, here’s the ground truth. According to the REALTORS® Association of Edmonton’s July 2026 market report, the Greater Edmonton Area recorded:
- 2,535 residential sales: down 11.0% from July 2025
- Inventory up 17.9% year over year
- 4,258 new residential listings
- Average residential selling price: $475,079: up 2.6% from July 2025
- MLS® Home Price Index composite benchmark: $429,100: essentially unchanged year over year
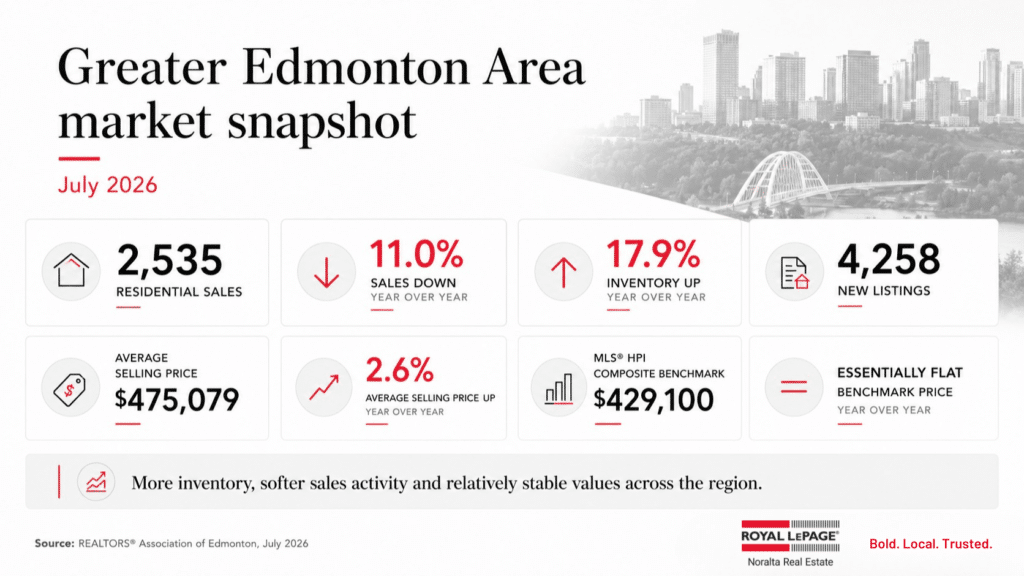
More inventory. Softer sales. Stable values. For a homeowner weighing a renewal decision, that combination matters: buyers have more choice and less urgency, but many Edmonton-area homeowners may have meaningful equity built into their properties, depending on when, where and what they bought. Every neighbourhood and price range behaves differently, so this is a starting point, not the answer.
The Alberta paradox
Nationally, 38% of mortgage holders surveyed expect their payment to rise at renewal. In Alberta, that number drops to 29%, the lowest of any region in the survey. Another 35% expect it to stay about the same, 12% expect a decrease, and 23% aren’t sure yet.
Here’s the part that matters more.
Among Alberta respondents who do expect an increase, 82% say it will put some level of financial strain on their household, the highest level reported among the provincial groups in the survey. Almost half, 49%, describe that strain as significant.
So: fewer Albertans expect a hit. But the ones who do expect to feel it hard. Pressure doesn’t automatically mean distress, and it doesn’t automatically mean selling. For most households, it means a budget conversation.
Asked what they’d change to absorb a higher payment, Alberta respondents said:
- 60% reduce or cut travel and vacations
- 56% cut discretionary spending (dining, entertainment, subscriptions)
- 52% reduce spending on essentials like groceries or gas
- 47% reduce or stop saving and investing
- 41% delay or cancel renovations

That’s a household planning issue for most people, not a housing crisis.
And most aren’t planning to move over it. 68% of Alberta respondents said they weren’t considering changing their living arrangements because of renewal. Of the 27% who were, the options ranged from downsizing to relocating to renting out part of the home.
Renewal as a checkpoint, not a trigger
A renewal doesn’t have to mean a move. But if a move, a renovation, or a downsize was already somewhere on your radar, the timing of your renewal can matter. Breaking a mortgage mid-term can carry a prepayment penalty, so reaching the end of a term creates a natural window to look at both financing and real estate plans before locking into another one.
Royal LePage Noralta Real Estate Broker/Owner Tom Shearer sees this play out regularly:
“What we’re seeing is that a mortgage renewal is becoming a natural checkpoint for homeowners. It doesn’t necessarily mean they need or want to move, but it is prompting people to look more closely at their housing costs, the equity they’ve built, and whether their current home still fits where they’re headed.
A renewal can also create a natural window for homeowners who are considering a property change. Making that change at the end of a mortgage term may allow a homeowner to avoid the prepayment penalty that can apply when a mortgage is broken early, depending on their mortgage terms. Many people intentionally time their move to align with a renewal.
In the Edmonton area, having a clear understanding of your property’s value and the options available in today’s market can make those conversations much more productive. The goal isn’t to create urgency. It’s to make sure homeowners have good local information before they make a decision.”
Tom Shearer, Broker/Owner, Royal LePage Noralta Real Estate
Worth asking yourself before your renewal date:
- Is this home still the right fit for the next three to five years?
- How much equity have we built?
- What’s the property realistically worth today?
- Would renovating make more sense than moving?
- What would downsizing, upsizing, or changing communities actually cost?
- Could part of the property generate rental income?
- Does the timing of our mortgage term affect when a move would make sense?
Sometimes the answer is “we’re staying.” That’s still a good decision when it’s an informed one. Knowing your property’s current value isn’t just for people about to list. It is useful context for conversations with your lender, mortgage professional, financial advisor or REALTOR®.
If that would help, Royal LePage Noralta Real Estate offers a home evaluation with a REALTOR® who knows your local market.
Your Mortgage Partner
Renewal questions? Vaughn is right down the hall.
Vaughn Leroux & Team with Dominion Lending Centres work out of our Edmonton office, so getting a second opinion on your renewal doesn’t mean starting from scratch with a stranger. Fast pre-approvals, straight answers, and mortgage solutions for renewals, refinances, first-time buyers, and investors.
Should you automatically renew with your current lender?
Not necessarily. Royal LePage’s survey found 45% of Alberta mortgage holders plan to review their options before deciding, 44% expect to stay with their current lender, and 10% intend to switch outright.
Mortgage products, penalties, portability provisions, and qualification requirements vary a lot. Talk to your lender or mortgage professional about your specific mortgage before making any real estate decision around it. For uninsured mortgages, OSFI currently sets the minimum qualifying rate at the greater of your contract rate plus two percentage points, or 5.25%. Confirm your own situation directly, as treatment can differ for certain straight switches at renewal.
For a plain-language breakdown of how rates work, our Understanding Interest Rates in Edmonton guide covers the Bank of Canada policy rate, lender prime rates, and how the bond market drives fixed rates.
Where rates stand
At the time of publication, the Bank of Canada’s target for the overnight rate is 2.25%, well below the post-pandemic peak. Even so, homeowners renewing five-year mortgages taken out during the low-rate years may still be stepping into a higher borrowing-cost environment than they left.
CMHC’s Spring 2026 Residential Mortgage Industry Report expects renewal volumes to decline through the rest of 2026, though borrowers coming off five-year terms may still see meaningful cost increases. Canada, broadly, is moving through the later stages of the pandemic renewal wave. Your own numbers matter more than the national trend line.
When a REALTOR® belongs in the conversation
Your REALTOR® doesn’t replace your lender, broker, accountant, or financial advisor. Each answers a different piece of the question. A mortgage professional handles financing terms and penalties. A financial advisor looks at your household’s broader picture. A local REALTOR® answers the real estate side:
- What could my home sell for today?
- What’s actually sold in my neighbourhood recently?
- How much inventory is out there?
- What would it cost to buy the type of home I’d move into?
- Is there strong demand for my specific property type?
Those answers matter whether you move next month, in three years, or never.
The bottom line
The 2026 mortgage renewal story in Alberta isn’t one of widespread panic. Alberta homeowners are the least likely group surveyed to expect a payment increase. But among those who do, the expected strain is real. And most aren’t planning to move because of it.
Know your mortgage options. Know your budget. Know what your property is worth. Know what the local market is doing. Then decide what makes sense for you.
Royal LePage Noralta Real Estate serves Edmonton and the surrounding area, including Sherwood Park, St. Albert, Spruce Grove, Fort Saskatchewan, Leduc, and neighbouring communities. Meet our Edmonton & Area REALTORS®.
This article is provided for general informational purposes only and is not mortgage, financial, legal, or tax advice. Mortgage products, prepayment charges, portability provisions, and qualification requirements vary. Speak with the appropriate qualified professional regarding your individual circumstances. Not intended to solicit buyers or sellers currently under contract.
Frequently asked questions about mortgage renewal in Edmonton (2026)
When should I start shopping my mortgage renewal?
About 120 days before your maturity date. Most lenders let you lock in a rate that early without penalty, and it gives you room to compare offers instead of accepting the first one that lands in your inbox. Federally regulated lenders are required to send your renewal notice at least 21 days before maturity… but 21 days is the legal minimum, not a good planning window.
Starting at 120 days gives you time to:
- Request your renewal offer and current balance from your lender
- Get two or three rate quotes, including straight switch options if you’re uninsured
- Decide whether to renew, switch, refinance, or use the renewal as a checkpoint for your broader housing plan
- Lock your rate and confirm any penalties or portability details if a move is on the table
What’s a “straight switch” and does it apply to me?
A straight switch is moving your mortgage to a new lender at renewal without increasing the loan amount or the amortization period. Since November 2024, OSFI no longer requires the mortgage stress test for straight switches on uninsured mortgages, which closed a gap that used to make switching harder than renewing.
Whether it applies to you depends on:
- Whether your mortgage is insured or uninsured
- Your lender’s specific policies
- Your income, credit, and property details
Your mortgage professional can confirm whether a straight switch is available to you and what rates are on the table.
Source: OSFI, Minimum Qualifying Rate for Uninsured Mortgages
What if my renewal is denied or I can’t qualify at the new rate?
You still usually have options. Depending on your situation, that can include:
- Switching to another A-lender that may underwrite your file differently
- Exploring B-lenders or alternative lenders, often at higher rates or fees but with more flexible qualifying criteria
- Secondary financing, such as a HELOC or second mortgage, alongside your main mortgage
- In some cases, selling to reset your housing costs before things reach default
The key variable is time. Starting the conversation well before your maturity date keeps every option open. Waiting until the last minute narrows the field fast.
Does renewal mean I have to move or sell?
No. Most Alberta homeowners surveyed in the Royal LePage 2026 Mortgage Renewal Survey weren’t planning to change their living arrangements because of renewal. For most, it’s a budget and financing checkpoint, not a trigger to move.
That said, if a downsize, upsize, renovation, or relocation was already somewhere on your radar, renewal timing can be a useful moment to review your home’s current value and equity, compare the cost of staying against moving, and align any property change with the end of your term to potentially avoid an early-break penalty.
How can a REALTOR® help if I’m not planning to sell?
Even if you’re staying put, a local REALTOR® can give you:
- A current market evaluation of your home
- Recent sales and active listings in your neighbourhood
- Inventory levels and demand for your specific property type
- What it would cost to buy the kind of home you might move into later
- Options like renting out part of your home, downsizing down the road, or using equity for renovations
That information is useful context for conversations with your lender, mortgage professional, and financial advisor. It helps you make informed choices about your biggest asset, whether or not a move is anywhere in the picture.
Should I just renew with my current lender to keep things simple?
Not necessarily. Many homeowners do stay put, but it’s worth at least reviewing your options. Royal LePage’s 2026 survey found 45% of Alberta mortgage holders plan to review their options before deciding, 44% expect to stay with their current lender, and 10% intend to switch outright.
Depending on your file, another lender might offer a lower rate, more flexible prepayment or portability terms, or a structure that better fits your plans, like a future move, a rental suite, or a refinance down the line. Your mortgage professional can run the numbers for your specific situation so you know what “simple” actually costs.
About the data
The Royal LePage® 2026 Mortgage Renewal Survey was conducted by Burson using the Leger Opinion online panel, surveying 1,127 Canadians aged 18+ renewing a mortgage between July 20 and August 6, 2026. Because the research used a non-probability online panel, no statistical margin of error applies. The survey reports provincial results for Alberta but not Edmonton-specific data. Greater Edmonton Area housing figures come separately from the REALTORS® Association of Edmonton.
Sources
Royal LePage® 2026 Mortgage Renewal Survey
royallepage.ca | full survey release
REALTORS® Association of Edmonton: July 2026 Market Statistics
realtorsofedmonton.com | July 2026 stats
Bank of Canada: 2026 Financial Stability Report, Households
bankofcanada.ca | Financial Stability Report
Bank of Canada: Policy Interest Rate
bankofcanada.ca | policy rate
OSFI: Minimum Qualifying Rate for Uninsured Mortgages
osfi-bsif.gc.ca | qualifying rate
CMHC: Residential Mortgage Industry Report
cmhc-schl.gc.ca | industry report
Ratehub.ca: Mortgage Renewal Process Guide
ratehub.ca | mortgage renewal timeline